Billing seems like the most routine part of administration, which is why it’s the first thing to be delegated improperly. The entire cycle is outsourced without distinguishing between the operational aspects and those that involve customer relations.
It’s a good idea to keep them separate before signing anything.
Which parts of the cycle can be delegated?
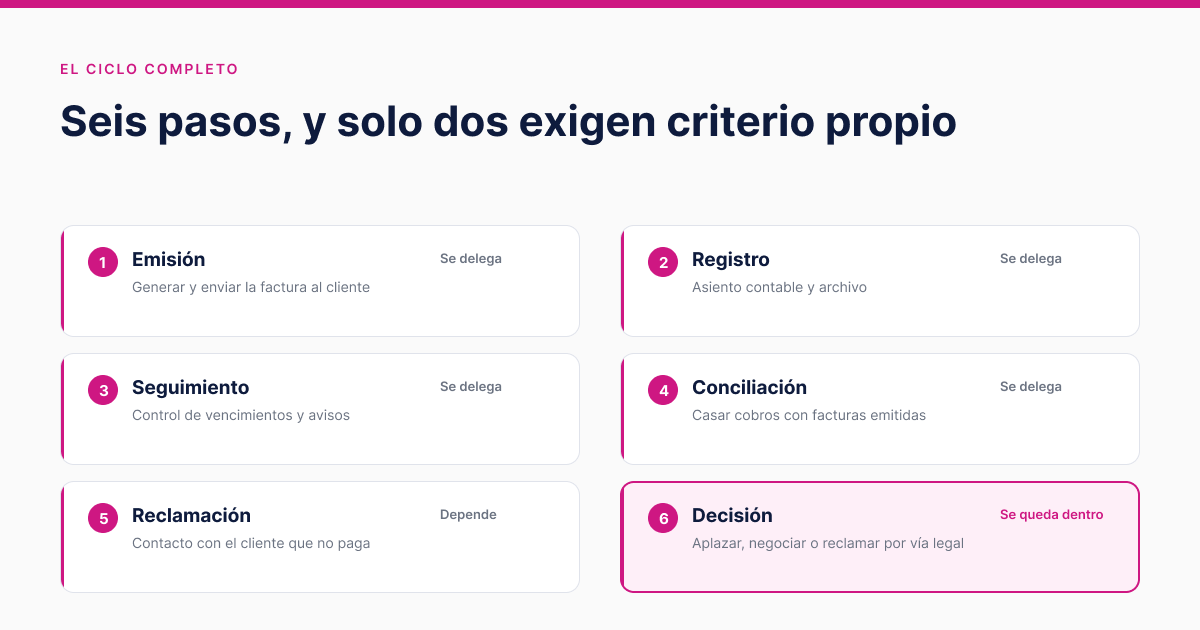
The cycle consists of six steps, and only the last two require a decision. The first four involve following clear rules.
| Step | What does this entail? | Who does it? |
|---|---|---|
| Broadcast | Generate and send the invoice | Delegates well |
| Registration | Accounting Entry and Filing | Delegates well |
| Follow-up | Due Date Tracking and Notifications | Delegates well |
| Work-Life Balance | Match collections with issued invoices | Delegates well |
| Complaint | Contact a customer who hasn’t paid | It depends on the customer |
| Decision | Defer, negotiate, or file a claim | It stays inside |
Debt collection is the area with the most nuances. Chasing a 300-euro payment from a small client is an administrative task. Calling your largest client because they haven’t paid in sixty days is not, and delegating that task could cost you more than the amount of the invoice.
Which duties can never be delegated?
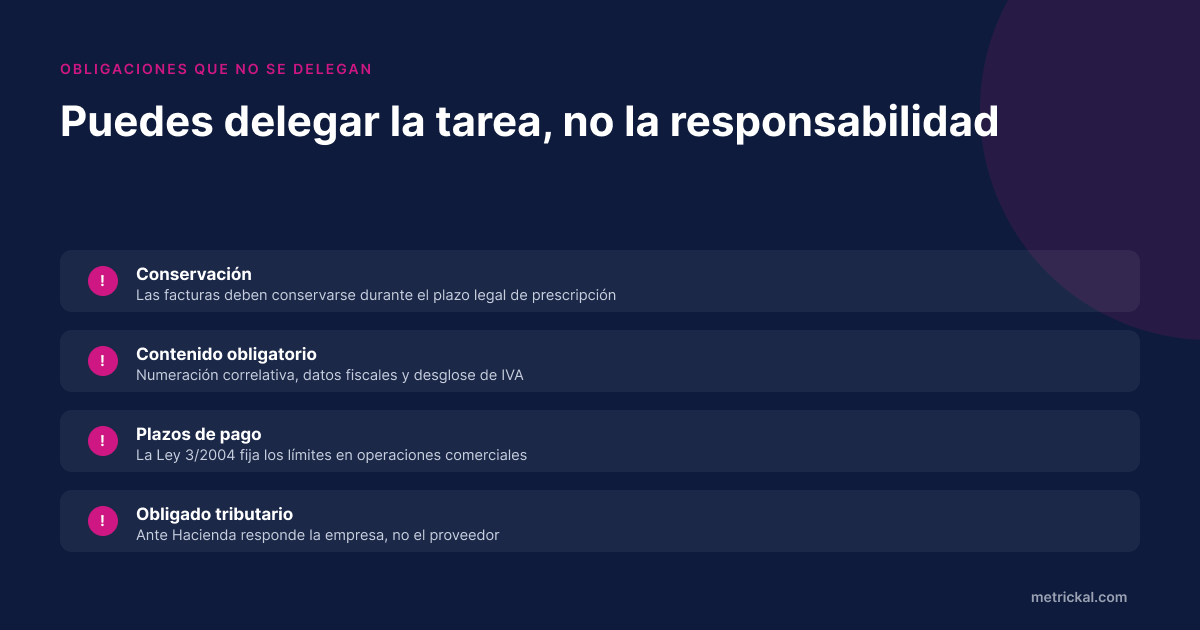
This is the part you should understand clearly before a problem arises.
- Conservation. Invoices must be retained for the statutory limitation period. Having a third party file them does not transfer this obligation.
- Required content. Sequential numbering, complete tax information, taxable base, and a breakdown of VAT. The issuing company is responsible for any procedural errors.
- Payment Terms. Law 3/2004 sets the maximum payment term between companies at 60 calendar days and the default term at 30 days if no agreement has been reached. Payments made after this deadline are void, and nonpayment automatically accrues late-payment interest plus a fixed compensation of 40 euros for collection costs.
- Taxpayer Status. Your company is responsible to the Tax Agency, never the supplier performing the work.
None of this is an argument against outsourcing. It’s an argument in favor of setting written deadlines, agreeing on a review process, and determining what happens when something is late.
How do you make the transition?
First, registration and filing
It’s what the customer doesn’t see. If something goes wrong, you catch it before it leaves the company.
Then, the broadcast
Here, real-time data is released, and a check is performed to see whether your numbering, series, and conditions were documented or were simply based on someone’s customary practice.
Finally, monitoring and reconciliation
This requires the team to be familiar with your payment terms for each customer. Until then, any payment reminder will be generic and will annoy those who don’t owe anything.
How it fits in with the rest of your administration
Billing is almost never outsourced on its own. It goes hand in hand with accounting and the rest of the back office:
- Outsource accounting, which runs concurrently with billing.
- Human resources outsourcing—especially if you also outsource payroll.
- Back office in Madrid and Bilbao.
- The complete map is in the ” Locations” section.
Frequently Asked Questions
Which parts of the billing process can be outsourced?
Issuing and sending invoices, bookkeeping, filing, tracking due dates with automatic reminders, and reconciling payments with issued invoices. These are tasks with clear rules, verifiable results, and recurring volumes.
Can the collection of unpaid debts be outsourced?
The operational side, yes: due date notices, reminders, and document tracking. It’s best to have someone from your company handle the conversation with an important client who isn’t paying, because in that case, you’re not just managing an invoice—you’re managing a business relationship.
Who is liable to the tax authorities if an invoice is issued incorrectly?
Your company. Outsourcing the processing does not change who is liable for the tax. That is why it is advisable to specify in writing who reviews the documents before they are issued, the deadline for submitting each batch, and what happens if an error reaches the client or appears on a quarterly tax return.
What are the legal requirements for an invoice in Spain?
Sequential numbering, date of issuance, complete tax information for the issuer and recipient, description of the transaction, taxable base, applicable VAT rate, and resulting tax amount. Invoices must be retained for the statutory limitation period, and this obligation rests with the company even if a third party files them.
What about the payment terms?
Law 3/2004 sets a maximum of 60 calendar days for transactions between businesses and 30 days by default in the absence of an agreement. Late payment interest accrues automatically upon nonpayment, without the need for a claim, and the creditor is also entitled to a fixed amount of 40 euros for collection costs. A supplier may notify you of payment due dates, but it is your company’s responsibility to meet those deadlines.
When Is It Worth It to Outsource Billing?
When the volume of invoices grows faster than your team, when reconciliation is done in batches instead of daily, or when the monthly closing depends on a single person. If you issue only a few invoices per month and the process is consistent, it’s not worth the effort to coordinate.
Where to Start
Take a look at how many invoices you issued last month and how many hours it took to issue, track, and reconcile them. If that number grows every quarter but your team doesn’t, you already have the answer.
If you’d like a calculation based on your numbers, let’s talk.
References: Invoicing and record-keeping requirements of the Tax Agency. Law 3/2004, of December 29, establishing measures to combat late payment in commercial transactions.